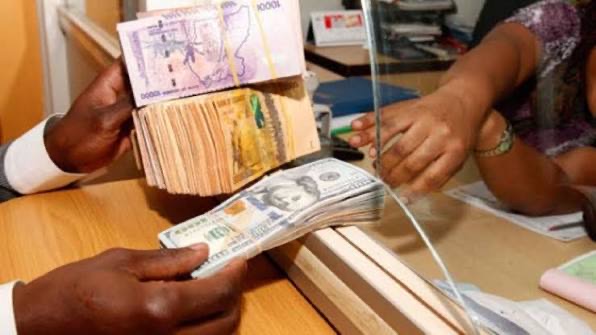
 Uganda’s currency is facing one of its most significant periods of depreciation in recent years, with the Shilling recently weakening beyond the Shs4,000-per-US-dollar level. The development is raising concerns over the cost of imports, inflation, business operations and the purchasing power of households.
The Shilling’s recent weakness has been driven by several factors rather than one single cause.
What is causing the depreciation?
One major factor is strong demand for US dollars. Importers, particularly those in the energy, manufacturing and merchandise sectors, require dollars to pay overseas suppliers. Recent reports also indicate that some businesses have been purchasing dollars ahead of the traditional end-of-year import season.
Uganda’s trade figures further illustrate the pressure. In July 2026, merchandise imports increased by 25.4 percent to US$1.61 billion, while exports grew by 10.1 percent to US$1.40 billion. The resulting trade deficit widened to about US$210 million.
Higher global fuel prices are another source of pressure. Uganda relies heavily on imported petroleum products, meaning that increases in international oil prices create greater demand for dollars while simultaneously increasing the country’s import bill.
There are also global financial pressures. Foreign investors adjusting their positions in Ugandan assets can increase demand for foreign currency, while international uncertainty can encourage investors to move funds into safer or more liquid assets.
What does a weaker Shilling mean for Ugandans ?
The immediate effect is more expensive imports.
An importer who previously needed Shs3.7 million to purchase US$1,000 would need approximately Shs4 million at an exchange rate of Shs4,000 per dollar.
That difference eventually affects consumers through higher prices for fuel, vehicles, machinery, electronics, medicines and other imported products.
Businesses that rely on imported raw materials may also increase their prices to compensate for higher operating costs. This can contribute to inflation and reduce household purchasing power.
Is depreciation always bad?
Not necessarily.
A weaker Shilling can make Ugandan exports more competitive because foreign buyers can purchase Ugandan products relatively cheaply in dollar terms.
However, this benefit depends on Uganda producing and exporting more. If exporters themselves depend heavily on imported fuel, machinery, fertilisers, packaging and other inputs, their costs will also rise.
The challenge, therefore, is ensuring that depreciation translates into higher export earnings rather than simply higher import costs.
What can Uganda do?
The solution should go beyond simply trying to defend a particular exchange-rate level.
First, Uganda needs to increase exports. Greater investment in agriculture, manufacturing, tourism, minerals and value-added products can generate more foreign currency.
Second, domestic production must be strengthened. Producing more of the goods currently imported can reduce pressure on foreign exchange, provided local production is competitive and efficient.
Third, Uganda needs to attract and retain foreign investment and other sustainable dollar inflows. Remittances, tourism receipts and investment contribute important foreign-exchange earnings.
Fourth, monetary policy must remain responsive. The Bank of Uganda has a mandate to maintain monetary and price stability and manage foreign-exchange policy.
Finally, policymakers need to address the structural trade imbalance. Uganda cannot sustainably depend on continuously rising imports while export earnings grow at a slower rate.
Conclusion
The falling Shilling is more than an exchange-rate story. It is a reflection of the broader relationship between what Uganda earns in foreign currency and what it spends abroad.
The recent surge in dollar demand, rising import costs and widening trade deficit demonstrate the vulnerability created by heavy dependence on imports.
While the Bank of Uganda can manage excessive volatility, long-term currency stability will ultimately depend on Uganda’s ability to produce more, export more, attract sustainable foreign investment and reduce unnecessary dependence on imports.
The Shilling’s current weakness should therefore be treated not only as a monetary challenge, but also as a call to strengthen Uganda’s productive capacity and build an economy that earns more foreign currency than it consumes.